
Hollis, Queens, NY
Sell your house fast in Hollis, Queens.
We buy Hollis houses as is for cash. Frame colonials and capes from the 1920s to the 1950s, two families off Jamaica Avenue, houses with a basement tenant, estates held since the 1970s, any condition.
$870,000
Median Hollis sale
72 days
Avg market days
+5.4%
YoY change
About the area
Why Hollis sellers call us.
Hollis is the neighborhood in southeast Queens between Jamaica and Queens Village, with Hillside Avenue on the north, Hollis Avenue on the south, Francis Lewis Boulevard on the east and the Long Island Rail Road station at 193rd Street in the middle. It was built between 1900 and 1955, frame colonials with porches on the numbered streets north of Jamaica Avenue, brick and frame capes south of the tracks, and bigger houses up the hill in Holliswood. It was Jewish and Irish through the 1960s, became one of the first Black middle class neighborhoods in Queens in the 1970s, and is Caribbean, African American and South Asian now, with families from Guyana, Trinidad, Jamaica and Bangladesh buying from the families who came in 1972. Those 1972 houses are estates, with children in Long Island, in Georgia and in the Carolinas, and a house that has a tenant in the basement and a boiler from the first Bush administration.
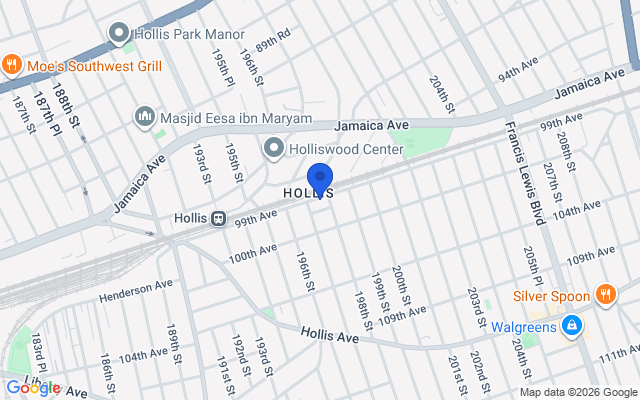
The typical home value in Hollis is around $870,000, up roughly 5.4% over the past year, with houses averaging about 72 days on the market.
The colonial your parents bought in 1972 and the children in Georgia
The most common Hollis call is a frame colonial on 199th or 203rd Street bought in the early 1970s, paid off in the 1990s, with a porch that needs posts, a roof with layers, a kitchen from 1985, a basement finished for a tenant, and fifty years of belongings. The parents are gone or in care, the children are in Hempstead, Atlanta and Charlotte, and Queens County Surrogate’s Court has the file. A listing agent wants the tenant out and the house emptied. We buy it full and occupied, wait for the letters, and each heir signs where they live.
The basement tenant and the second kitchen
Most Hollis houses have a full basement, and a large share of them have a kitchen, a bathroom, a side entrance and a tenant, often a relative, often paying cash. A basement apartment in New York City needs a permit and a certificate of occupancy that almost none of these have. The appraiser notes the second kitchen, the lender wants it removed, and the financed buyer walks or asks for a cut at the end. A 311 complaint brings a Department of Buildings inspector and a violation. We buy the house as its legal rooms, with the violation open, and handle whoever is downstairs on terms worked out with you.
The two family off Jamaica Avenue with a tenant in court
The two families near Jamaica Avenue and Hollis Avenue were bought for the income, and the income has not kept up. A tenant who stopped paying in 2021, a Queens Housing Court case adjourned since, a water bill in the thousands with a lien sale behind it. We buy occupied, on the rent actually arriving, with the case open and the water balance paid at closing out of the price.
Reverse mortgages, modifications and the loans from 2006
Hollis was hit hard by the subprime years and a good number of its houses carry a loan from 2005 or 2006 that was modified once and is behind again, or a reverse mortgage that came due when a parent died. Queens County Supreme Court foreclosures take years, and a reverse mortgage servicer gives the estate six months. Both windows are openings. A cash closing before the referee’s date or the servicer’s deadline pays the loan and leaves the remaining equity with the family.
Where listing still wins in Hollis
A renovated colonial with a legal basement, a current boiler and no deadline should be listed, and we will say so, because first time buyers with FHA loans are waiting for exactly that house in Hollis. Where a cash sale wins is the estate with heirs in three states, the basement tenant the appraiser will flag, the tenant in Housing Court, the loan from 2006, the reverse mortgage with a deadline, or the owner who needs it done by a date.
What we buy in Hollis
Frame and brick colonials, capes and two families, houses with a basement unit or an open violation, houses in Holliswood, mixed use buildings on Jamaica Avenue, Hillside Avenue and Hollis Avenue, estates in any condition, houses in foreclosure, and vacant lots. We do not buy cooperative apartments. If you own something unusual, call anyway.
North of Jamaica Avenue, south of the tracks, and Holliswood
Hollis is priced by the railroad. North of Jamaica Avenue toward Hillside, the frame colonials on the numbered streets are priced on the block and the condition and sell to families from Jamaica and Queens Village with FHA loans. South of the Long Island Rail Road tracks toward Hollis Avenue, the capes and two families are priced on the rent and the legal units. Holliswood, up the hill north of Hillside Avenue, is bigger houses on bigger lots and the top of the market. We build the offer from sales on your side of the tracks, with the comparable addresses on the sheet, and we show you which band your house is in before we show you the number.
What the bands share is the frame build from 1910 to 1950. A Hollis house that was never renovated carries the same list: a porch on rotted posts, a roof with three layers, knob and tube on the second floor, a basement kitchen with a side door, galvanized pipes, a boiler from 1991 and a service panel from 1960. A lender’s inspector writes it all down. We read the same list and price it, and the house closes anyway.
Reverse mortgage deadlines and the six month clock
A reverse mortgage comes due when the last borrower dies or leaves the house, and the servicer gives the estate six months to pay it, with extensions of ninety days available twice if the estate asks and shows the house is being sold. A listing that falls apart at the appraisal eats the first six months. We close inside the window, the loan is paid at the table from the price, and whatever is left above the balance goes to the estate. If the loan is more than the house is worth, the estate owes nothing beyond the house, and we handle the servicer’s short sale paperwork ourselves.
Looking just beyond Hollis? You can also sell your house fast in Jamaica NY or sell a house fast in Queens Village NY, and you can read about how we buy houses in St. Albans NY.
Many Hollis homeowners also ask us how to sell a house in foreclosure in Hollis NY, sell an inherited home, or sell a house during divorce.
How a sale like this goes in Hollis
203rd Street Between Hillside and Jamaica: a 1926 Frame Colonial, a Reverse Mortgage Due in March, a Tenant in the Basement Since 2015, Three Heirs in Hempstead, Atlanta and Charlotte
Their father bought the frame colonial on 203rd Street in 1972, the year he made sergeant at the 103rd Precinct. He took a reverse mortgage on it in 2013 after their mother died, and finished the basement for a tenant in 2015 to cover what the loan did not. He died in the house in September 2024 at eighty six. The servicer's first letter came in October and gave the estate until March. The oldest son lived in Hempstead, the daughter in Atlanta, the youngest in Charlotte. The tenant in the basement paid cash and had a side door.
The Hempstead son listed it in November 2024. The agent wanted the tenant out and the basement kitchen removed before photos. The first buyer was FHA. The appraiser found the basement unit and the lender declined in January. The servicer's second letter came in February with the March date on it. The daughter in Atlanta called an attorney in Jamaica who told her the estate could ask for an extension and might not get one.
The attorney called us in February. The offer was written on the house as it stood: a porch with two rotted posts, a roof with three layers, a 1985 kitchen, a boiler from 1991, the basement as a basement with the tenant staying ninety days on terms the three of them set, and fifty two years of a sergeant's belongings as a cleanout line. One page, the same page to all three heirs and to the attorney. A closing date set for the first week of March, inside the servicer's deadline, because the Surrogate's letters had issued in January.
The Atlanta daughter and the Charlotte son signed with notaries. We closed on March 5 at a title company on Hillside Avenue. The reverse mortgage was paid at the table and the servicer's file was closed the next week. The tenant moved in May. The Hempstead son took the photographs, the flag from the funeral and his father's shield from the dresser. What he said was that the agent had told them the basement was the problem, and the deadline had been the problem.
Illustrative. Based on the situations we buy in across Hollis. A composite, not a single transaction, with details changed.
Common reasons Hollis sellers call us.
A frame colonial on 203rd Street your parents bought in 1972
Heirs in Hempstead, Atlanta and Charlotte, a Queens Surrogate's file, a porch that needs posts and fifty years inside. We buy it full and each heir signs where they live.
A basement apartment with a side door and a cousin paying cash
No lender counts it. We price the basement as a basement, buy the house as its legal rooms, and handle the cousin on terms the family sets.
A reverse mortgage that came due when your father died
The servicer gives the estate six months and then files. A cash closing inside that window pays the loan and the rest is the family's.
A 2006 loan modified in 2012 and behind again since 2023
Queens County foreclosures take years and that is the opening. A cash closing before the referee's date pays the bank and leaves the equity with you.
A tenant off Jamaica Avenue who stopped paying in 2021
Queens Housing Court is slow. We buy on the rent actually coming in and the case transfers to us at closing.
A water bill in the thousands and a lien sale notice from the city
The balance comes off the price at closing, listed on the offer, and clears when the deed records.
A Department of Buildings violation from a 311 call about the basement
The violation ends a financed sale. We buy with it open and clear it ourselves after closing.
A move to Charlotte with the new house closing in three weeks
We set the Hollis closing around it, about 14 days out, and nothing waits on a bank.
Frequently asked questions about selling in Hollis.
How quickly can you buy a house in Hollis?
Send the address through the form or call (516) 964-7222. We see the house, you get a written offer within 24 hours with the comparable sales on it, and you pick the closing. About 14 days when the title is clean, two to four weeks with an estate or a lien.
There is a tenant in the basement with a separate entrance. Can you still buy?
Yes. A basement unit without a certificate of occupancy is not a legal apartment in New York City, so we price the house as its legal rooms and the basement as a basement. Whoever is downstairs is handled on terms worked out with you before closing, and any Department of Buildings file comes to us.
The reverse mortgage servicer is sending letters. How long do I have?
Usually six months from the death, with extensions available on request, before the servicer files to foreclose. We close inside that window. The loan is paid from the price at closing and the remaining equity goes to the estate.
My brother is in Atlanta and my sister is in Charlotte. Do they have to come to Queens?
No. Each heir signs with a notary where they live, our title company prepares the packages, and we coordinate with the Queens County Surrogate's Court file and the estate attorney. A neighbor can let us in for the walkthrough.
My tenant has not paid since 2021 and the case keeps getting adjourned. Do I wait?
No. We buy occupied Hollis two families with a Housing Court case open. The offer is built on the rent actually arriving and the case transfers to us at closing.
Would an agent get me more?
Sometimes, and we say so. A renovated colonial with a legal basement and no deadline usually nets more listed, because FHA buyers are waiting for it. Ours is the better route when the house is an estate with heirs in three states, the basement has a tenant, a loan or a reverse mortgage has a deadline, a tenant is in court, or you have a date.
How do you figure the offer?
Recent sales on your side of Jamaica Avenue, minus the work the house needs, minus carrying and resale costs, minus our margin. The basement, the roof, the boiler and any city balance are each a line, and the sheet is yours before you sign.
What comes off the price?
Your payoff, any liens or water balances, and the New York State and City transfer taxes, each itemized on the offer. No commission, no fees, and we pay our own closing costs.