
Shelton, CT, CT
Sell your house fast in Shelton, CT.
We buy Shelton houses as-is for cash. Huntington, White Hills and downtown, wells and septic included, any condition.
$590,000
Median Shelton sale
38 days
Avg market days
+4.5%
YoY change
About the area
Why Shelton sellers call us.
Shelton is two places stacked on one hillside. Down along the Housatonic is the old mill city, dense and industrial, where rubber and tack works once employed most of the town. Up the hill is Huntington and White Hills, which is suburban, spread out, and largely built after the war on land that used to be farms. Route 8 brought corporate offices in and changed the tax picture entirely.
The typical single family home value in Shelton is around $590,000, up roughly 4.5% over the past year, with houses averaging about 38 days on the market.
Why Shelton taxes are genuinely low, and what that means for you
This is worth knowing because it changes the arithmetic on holding versus selling. Shelton’s mill rate for 2026 to 2027 is 15.51. The Connecticut statewide average sits around 28, Bridgeport is 27.95, and Hartford is 68.95. Shelton runs at roughly half the state average and well under a quarter of Hartford.
The corporate office development along the Route 8 corridor is a large part of why. Commercial property carries a meaningful share of the grand list, which holds the residential rate down.
Practically, it means the cost of holding a Shelton house is lower than almost anywhere else in Fairfield County. If you are deciding whether to wait out the market, the carrying cost pressure here is genuinely smaller than it would be in Bridgeport or Hartford. We would rather tell you that than pretend urgency you do not have. Where speed still matters is when a house is empty, needs work a lender will flag, or you have a date to be somewhere else.
Wells and septic up the hill
A large share of Huntington and White Hills sits on private well water, a septic system, or both. Lots are big, the houses are set back, and municipal service never reached a lot of it.
Most owners never think about any of that until a buyer’s lender does. A financed buyer generally needs a well water test and a septic inspection before the loan funds. A failing septic is one of the most expensive surprises in residential real estate and replacement runs well into five figures. Owners who have had no trouble in twenty five years frequently cannot say how old the system is or where the leaching fields run, because the paperwork went with an earlier owner.
We buy on well and septic, including systems known to be failing and systems nobody can assess. There is no lender in a cash sale, so there is no inspection contingency to clear first.
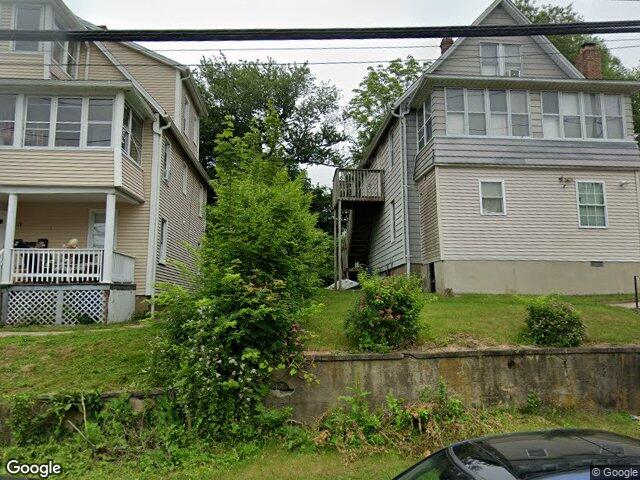
The older stock down the hill
The blocks nearer the river and the old Howe Avenue commercial spine carry housing that is a century old or close to it, including two and three family frames built for mill workers. What we find in them is predictable: knob and tube wiring still energised, galvanized supply lines, cast iron waste stacks patched repeatedly, original boilers, and roofs carrying more than one layer. Some have had a unit added in the attic or the cellar at some point with nothing filed.
All ordinary, all exactly what an FHA or VA appraiser writes up, and all reasons a perfectly livable house loses a financed buyer two months into a contract.
Two Connecticut points before you sell
The conveyance tax is paid by you, the seller, in a state portion and a municipal portion. Anybody who has sold in New York expects the buyer to carry more of the transfer cost and that is not how Connecticut works. It comes out of your proceeds and your closing attorney calculates it exactly.
Connecticut is an attorney state, so a licensed Connecticut attorney runs your closing rather than a title company. Good for you, and no obstacle for us.
What we buy in Shelton
Single family houses throughout Huntington and White Hills, including large lots on well and septic. Two and three family frames on the older blocks near the river. Houses that need a roof, a furnace, a panel, or all three. Estates where the heirs live elsewhere. Houses with tenants in place. Properties with liens or arrears, which are paid from the proceeds at closing rather than out of your pocket first.
What we do not buy is condominium or co-op units, and we will say so immediately.
The Housatonic, the old industrial strip, and what sits underneath it
The flat land along the river was where Shelton’s factories stood, and some of that footprint has been redeveloped while some of it has not. Housing built close to a former industrial parcel occasionally sits near ground with a history, and a buyer’s attorney or a cautious lender will sometimes ask questions about it that an owner cannot answer.
There is a related and more common issue: older houses on that side of town frequently had oil heat, and the tanks were often buried in the yard and then abandoned in place when the house converted to gas. A tank sweep turns them up, and a financed buyer’s lender wants the tank tested, removed, or both before it funds. That one finding has ended more Shelton contracts than anything else we hear about.
We buy with buried tanks in the ground, tested or untested, and with whatever the parcel history turns out to be. We price it and show you that line rather than asking you to resolve it first.
What Route 8 did to the town, and what it means for your house
The corporate office development along the Route 8 corridor reshaped Shelton in a way that most Connecticut towns never experienced. It brought jobs, it widened the grand list so commercial property carries a real share of the tax burden, and it is the main reason the residential mill rate sits at 15.51 rather than closer to the state average near 28.
For a homeowner that is genuinely good news and it is worth understanding what it does and does not mean. It lowers your cost of holding, which is why we tell Shelton sellers plainly that patience is cheaper here than in Bridgeport or Hartford. It does not make a dated house easier to finance, it does not fix a failing septic, and it does not shorten the time a retail sale takes when an appraiser writes up the roof.
So the decision here is usually not about tax pressure. It is about whether the house can get through a financed closing as it stands, and whether you have a date you need to meet.
How to reach us
Call (516) 964-7222 or send the address through the form. Written offer within 24 hours with the reasoning shown, including what we think the work costs, open for seven days, and you pick the closing date. More on how we buy across Connecticut and our how it works page shows the offer maths.
Looking just beyond Shelton? You can also sell your house fast in Bridgeport NY or sell a house fast in Danbury NY, and you can read about how we buy houses in Norwalk NY.
Many Shelton homeowners also ask us how to sell a house with code violations, sell a house with a tax lien, or sell a water damaged house.
Recent Shelton transaction
A White Hills Colonial on Two Acres, Sold After the Septic Failed Twice
They bought in 1988 on two acres up in White Hills, on a well and a septic system they had never once had trouble with. Thirty seven years later they were both in their seventies, the driveway was a problem every winter, and their son had found them a place near him in Wilmington with a closing date in October.
They listed in June and had an offer in eleven days, which felt like the easy part. The septic inspection failed. The leaching fields were original to the house and had reached the end of their life. The quote to replace came in at a number that would have taken a meaningful bite out of the sale, and the lender would not fund with a failed system. The buyer asked them to replace it. They offered to split it. The buyer walked in August.
The second buyer's lender wanted the septic re inspected, which nobody had repaired, plus a well water test. There was also a screened porch added in 2001 that appeared nowhere on the certificate of occupancy.
By September the Wilmington closing was five weeks out and they were looking at either paying for a septic system on a house they were leaving or losing the deposit on the new one.
Nick York walked the property on a Tuesday, looked at the fields, the well head, the porch and the roof, and wrote the offer the following morning with the septic replacement and the unpermitted porch shown as separate lines so they could see exactly where the number came from.
They closed in twelve days, three weeks before the Wilmington date. The septic became ours. They left the snowblower in the garage.
Common reasons Shelton sellers call us.
A septic system a lender will not accept
Much of Huntington and White Hills is on private systems. A failed inspection is a five figure problem that ends financed deals. We buy without the contingency.
Well water that has never been tested
A financed buyer needs a water test before funding. We do not, and we do not ask you to arrange one.
A house up the hill that needs everything at once
Roof, furnace and panel together is a number most sellers do not want to spend on a house they are leaving.
An older two family near the river with an unfiled unit
Attic and cellar conversions on the old mill blocks are common and rarely on the record. A lender cannot look past it.
An estate the family cannot manage from out of state
Large lots and old systems are hard to maintain remotely. We buy as the property sits.
Tenants in place
A retail buyer needs vacancy. We buy occupied and the tenancy becomes ours at closing.
Liens or arrears you cannot clear up front
They are paid from the sale proceeds, with the arithmetic shown to you in writing beforehand.
A date somewhere else
Relocations and closings on a next house do not wait for a mortgage contingency. We close on your date.
Frequently asked questions about selling in Shelton.
How do I sell my house fast in Shelton?
Call (516) 964-7222 or send the address through the form on this page. We look at the property, give you a written cash offer within 24 hours with the reasoning shown, and you pick the closing date, usually seven to fourteen days out. No agents, no repairs, no commissions.
My house is on a well and septic. Do I need them inspected first?
Not to sell to us. A financed buyer generally needs a well water test and a septic inspection before their lender funds, and a failing septic is one of the most expensive problems in residential real estate. We buy on well and septic including failing systems and systems nobody can assess, and we show you how we priced it.
Are Shelton property taxes really lower than the rest of the county?
Yes. Shelton runs a mill rate of 15.51 for 2026 to 2027 against a statewide average near 28. Bridgeport is 27.95 and Hartford is 68.95. The corporate development along Route 8 carries a real share of the grand list, which holds the residential rate down. It means your cost of holding is lower here than almost anywhere in Fairfield County, and we would rather tell you that plainly than manufacture urgency.
Should I just wait and list it instead?
Sometimes yes, and we will say so. For a well maintained Shelton house in good condition with no deadline, listing conventionally usually nets more. Where a cash sale wins is when the house needs work a lender will flag, the septic is questionable, the property is sitting empty, or you have a date to be somewhere else. We will tell you which situation you are in.
Who pays the Connecticut conveyance tax?
The seller does, in two parts, a state portion and a municipal portion. People who have sold in New York usually expect the opposite. It is deducted from your proceeds at closing and your Connecticut closing attorney calculates the exact figure.
Do I need a Connecticut attorney?
Yes. Connecticut is an attorney state, so a licensed Connecticut attorney handles the closing rather than a title company running it. That works in your favour because somebody whose job is to protect your side reads the contract. Tell us early if you do not have one.
Will you buy a two family on the older blocks near the river?
Yes. The mill era housing down the hill is often a century old with knob and tube, galvanized lines and original boilers, and sometimes an attic or cellar unit that was never filed. All of that stops a financed buyer. None of it stops us.
How fast can you close?
Seven to fourteen days is typical once the attorneys have what they need. We can move faster when a deadline requires it and slower if you need time for probate or to find your next place. You pick the date.