
Stamford, CT, CT
Sell your house fast in Stamford, CT.
We buy Stamford houses as-is for cash. North Stamford, Springdale, Glenbrook, Shippan and the Cove, any condition.
$840,000
Median Stamford sale
38 days
Avg market days
+8.6%
YoY change
About the area
Why Stamford sellers call us.
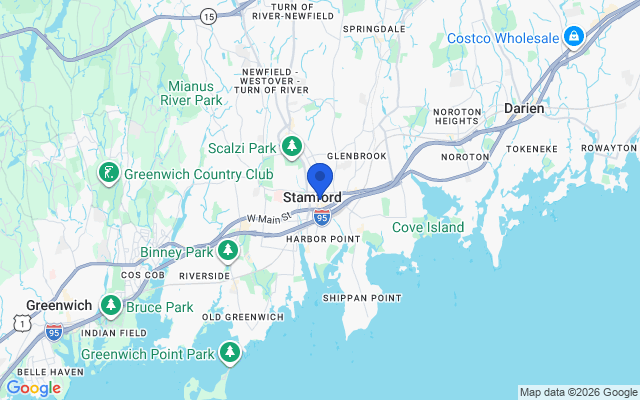
Stamford is really two housing markets sharing one city line, and which half your house sits in changes almost everything about selling it. North of the Merritt you have large lots, wells and septic systems, and houses set well back from the road. South of it, running down to Long Island Sound through Glenbrook, Waterside, Shippan and the Cove, you have denser blocks, older stock, and flood maps that matter.
The typical single family home value in Stamford is around $840,000, up roughly 8.6% over the past year, with houses averaging about 38 days on the market.
Why Stamford sellers call us
Stamford calls tend to come from people with a deadline rather than people with a bad house. A corporate relocation with a start date. A divorce where neither party wants to spend four months on showings. An estate where the heirs live in three states and the house has sat empty through a winter. Occasionally a landlord who has had enough of a two family in Glenbrook.
Values here are high enough that the percentages people worry about are large numbers, so it is worth being direct: a cash sale is not the highest price you can get for a well maintained Stamford house in good condition. What it is, is certain and fast. If the house needs work, or the timeline is the binding constraint, the gap between the two narrows considerably once you account for carrying costs, commissions and the repairs a financed buyer will demand anyway.
North Stamford: wells, septic, and what a lender asks for
A large share of North Stamford is on private well water, a septic system, or both. That is normal and most owners never think about it, right up until a buyer’s lender does.
A financed buyer generally needs a well water test and a septic inspection before the loan funds. A failing septic is one of the most expensive surprises in residential real estate and replacement runs well into five figures. Owners who have had no trouble for twenty years often have no idea how old the system is or where the leaching fields actually run, because the paperwork went missing three owners ago.
We buy on well and septic, including where the system is known to be failing or where nobody can say what condition it is in. There is no lender in a cash sale, so there is no inspection contingency to satisfy first.
The shoreline side: flood zones and insurance
Shippan, the Cove, Waterside and the blocks nearest the Sound carry flood zone questions, and they are what stops financed sales down there. A lender wants an elevation certificate and a flood insurance binder before it will fund, and on an older low lying house the premium can be large enough to break the buyer’s monthly number after they are already under contract.
Flood maps also get redrawn, and nobody writes to tell you your zone changed. Owners are regularly surprised mid sale by a designation they did not know applied to them.
We buy waterfront and near water houses in Stamford as they are. No elevation certificate, no binder, no lender.
Older stock, additions, and the certificate of occupancy
Plenty of Stamford housing dates to the 1920s through the 1950s, and a great deal of it has been extended, dormered or finished out at some point in the decades since. Work done in the 1970s and 1980s frequently was not permitted, or was permitted and never signed off.
When a financed buyer’s appraiser measures more house than the certificate of occupancy describes, the lender needs that reconciled. Resolving it means opening a file with the City of Stamford about work performed by somebody who may be long gone, and it takes months rather than weeks.
We buy the house as built. You are not expected to legalise a 1984 family room before we make an offer.
Two Connecticut points worth knowing
The conveyance tax here is paid by you, the seller, in two parts, a state portion and a municipal portion. Anyone who has sold in New York expects the buyer to carry more of the transfer cost, and that is not how it works in Connecticut. On a Stamford house at these values it is a real number, and your closing attorney will calculate it exactly.
Connecticut is also an attorney state. A licensed Connecticut attorney runs the closing rather than a title company. That is good for you, and it does not slow us down. If you do not have one yet, say so early.
What we buy in Stamford
Single family houses across North Stamford, Springdale, Belltown, Glenbrook, Newfield and Turn of River. Two families in the denser south end blocks. Houses on well and septic. Houses in flood zones. Estates that have been empty since the heirs went back to wherever they live. Houses with dated kitchens and original baths that a retail buyer would ask you to gut first. Houses with a tenant in place.
What we do not buy is co-op or condominium units, and we will tell you that in the first minute rather than waste your time.
How to reach us
Call (516) 964-7222 or send the address through the form. Stamford is about forty minutes from our office in Great Neck, so we can usually look at the property quickly. You get a written offer within 24 hours with the reasoning shown, and it stays open for seven days. More on how we buy across Connecticut and on our how it works page.
Looking just beyond Stamford? You can also sell your house fast in Hartford NY.
Many Stamford homeowners also ask us how to sell a house with code violations, sell a house with a tax lien, or sell a water damaged house.
Recent Stamford transaction
A North Stamford Colonial, Sold When the Septic Failed Two Weeks Before Closing
They had raised three children in the house and bought it in 1994, on two acres with a well and a septic system they had never once thought about. He took a role in Charlotte with a start date in eight weeks and they listed immediately, which in Stamford in the spring felt like plenty of time.
The first buyer was financed and moved quickly. The septic inspection came back failed. The leaching fields had reached the end of their life, the quote to replace came in at a number neither side wanted to absorb, and the lender would not fund with a failed system. The buyer asked them to replace it. They asked the buyer to split it. Neither happened and the contract ended six weeks before the start date.
The second buyer's lender wanted a well water test and then a re inspection of the septic, which nobody had repaired. There was also a sunroom off the back that had been added in 1998 and appeared nowhere on the certificate of occupancy, which the appraiser noticed.
By then he had a week before the drive to Charlotte and she was going to stay behind in a rental to manage a sale that had stopped moving.
Nick York walked the property on a Saturday, looked at the fields, the well head, the sunroom and the roof, and wrote the offer the following morning with the septic replacement and the unpermitted sunroom shown as separate lines.
They closed in eleven days, ten days before his start date. The septic became ours. She drove down with him instead of staying.
Common reasons Stamford sellers call us.
A relocation with a start date
Stamford runs on corporate employment and transfers come with deadlines. We close on your date rather than on a buyer mortgage timeline.
Well and septic a lender will want tested
Much of North Stamford is on private systems. A failing septic is a five figure surprise that ends financed deals. We buy without an inspection contingency.
A shoreline house with flood exposure
Elevation certificates and flood premiums break financed contracts in Shippan and the Cove. A cash sale needs neither.
An addition that was never signed off
Work from the 1970s and 1980s often does not match the certificate of occupancy. Reconciling it with the city takes months. We buy the house as built.
Divorce where neither side wants four months of showings
A clean sale on a fixed date is worth more than a few percent to most people in that position.
An estate standing empty through a Connecticut winter
Vacant houses freeze, and vacancy insurance is expensive when it can be written at all. Carrying costs at Stamford values are significant.
A dated house a retail buyer wants gutted first
Original kitchens and baths are what retail buyers discount hardest and lenders flag. We price the work and buy it as it is.
A two family with a tenant in place
Retail buyers need vacancy. We buy occupied and the tenancy transfers to us at closing.
Frequently asked questions about selling in Stamford.
How do I sell my house fast in Stamford?
Call (516) 964-7222 or send the address through the form on this page. Stamford is roughly forty minutes from our Great Neck office, so we can usually walk the property within a day or two. You get a written cash offer within 24 hours with the reasoning shown, and it stays open for seven days. No agents, no repairs, no commissions.
My house is on a well and septic. Do I need them tested before selling?
Not to sell to us. A financed buyer generally needs a well water test and a septic inspection before their lender funds, and a failing septic is one of the most expensive problems in residential real estate. We buy on well and septic, including where the system is failing or where nobody knows its condition, and we show you how we priced it.
Will a flood zone stop my Stamford sale?
It stops financed sales more often than people expect. Near the Sound in Shippan, the Cove and Waterside a lender wants an elevation certificate and a flood insurance binder, and the premium can break the buyer monthly payment after they are already under contract. There is no lender in a cash sale, so neither document is required.
Who pays the Connecticut conveyance tax in Stamford?
The seller does, in two parts, a state portion and a municipal portion. People who have sold in New York usually expect otherwise. At Stamford values it is a meaningful number, it comes out of your proceeds at closing, and your closing attorney calculates it exactly. We will show you the figure in writing before you agree to anything.
The house has an addition that was never permitted. Is that a problem?
Not for us. A lot of Stamford work from the 1970s and 1980s was either unpermitted or permitted and never signed off. A financed buyer stalls because the appraiser measures more house than the certificate of occupancy describes and the lender needs it reconciled with the city, which takes months. We buy the house as built.
Will I get less than listing with an agent?
For a well maintained Stamford house in good condition, usually yes, and we will say so plainly. What you get instead is a fixed date and no contingencies. Where the gap narrows sharply is when the house needs work, sits in a flood zone, is on an ageing septic, or you are carrying it empty, because then you are comparing our number against months of carrying costs, commissions and the repairs a lender will require anyway.
Do you buy condos or co-ops in Stamford?
No. We buy houses, two families and small multifamily only. Stamford has a lot of condominium inventory and we would rather tell you in the first minute than have you spend weeks on it.
How fast can you close?
Seven to fourteen days is typical once the attorneys have what they need, and Connecticut is an attorney state so a licensed Connecticut attorney will run your closing. If you need longer for a relocation date, a school year, or probate, you pick the date instead.
We also buy in nearby CT neighborhoods.
Ready to sell your Stamford house?
Submit your address. We respond within 24 hours.
Get my cash offer